A question of trust
Fiona Watson believes that accountants are critical to steering business through the climate change crisis. In her ICAS Sustainability Summit 2026 keynote speech, she explored how CAs have the skills to interrogate assumptions, understand consequences and provide assurance. Fraser Allen reports
Fiona Watson may jokingly refer to herself as “an amateur accountant” but 25 years of experience across law, banking and sustainability have led her to believe that it’s time for the accountancy profession to step up and tackle the complex challenges of sustainability. “My boss, Peter Bakker, once said that accountants will save the world,” she told the ICAS Sustainability Summit 2026 in Edinburgh in October. “If that’s true, we certainly have work to do.”
Watson is Vice President, Corporate Performance & Accountability at the World Business Council for Sustainable Development (WBCSD), an association of around 230 large organisations “leaning into the sustainability challenge”. Although based in Amsterdam following spells working in New York and London, Watson is originally from Edinburgh – she was Head of Legal for Treasury, Disclosure and ESG at RBS Group (now NatWest) in the aftermath of the financial crisis, from 2011–20. She also worked in senior roles for Amazon in Luxembourg and Amsterdam from 2020–23 where she led on EU Green Deal and global ESG reporting initiatives.
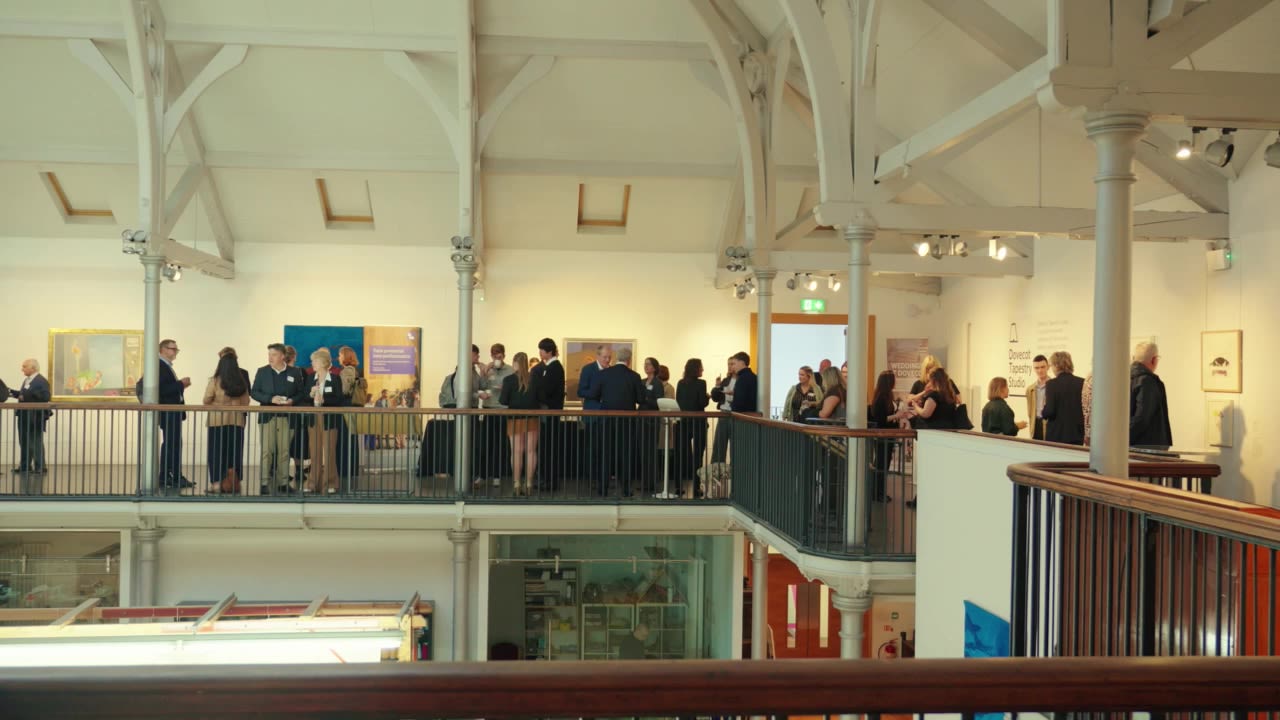
A quick look back at this year’s ICAS Sustainability Summit
A quick look back at this year’s ICAS Sustainability Summit
The dual-qualified lawyer (in both the UK and the US) therefore brought a wealth of experience to the summit, and began her keynote speech by looking forward to 31 December 2030 – the deadline for achieving the United Nations’ 17 Sustainable Development Goals.
“When we look back in 2030, what will we want to say we helped to achieve or helped avert?” she said. “The contribution of the profession of accountants is to help test the business case, including the assumptions about execution and financial returns. We need to trace each relevant exposure to the financial consequences – that is where accountants can make the evidence useful. You bring the experience in controls and professional judgement.”
Starting point
“Long before change happens and appears in a report, it appears in decisions,” Watson added. “A forecast assumes something about future costs and demand. An investment proposal assumes an asset will operate under certain conditions. A procurement decision assumes that a supplier will keep delivering. Those assumptions all shape the outcomes we eventually report. However, if we wait until the outcome appears in the report, some of our opportunities to respond may already have passed.”
Watson urged CAs to think about one significant decision their organisation is currently making. “How long will its consequences last? What conditions does it depend on? What evidence would make you pursue a different course?”
“It would be very convenient if a flood stopped at the edge of the consolidation perimeter, but nobody sent the river our accounting manual”
Critical to this is the concept of ‘double materiality’ that urges businesses to both assess their impact on the environment and the environment’s impact on them. “But it starts with a decision,” said Watson. “What could change the outcome enough to matter? What does the business depend on? What consequences could its activities create for others, and how might those consequences change the conditions in which it operates? For example, a water-intensive business may depend on reliable access to water but it may also affect local water availability. Understanding both perspectives can improve the questions that management asks about building its resilience.”
But as Watson points out, nothing is clear-cut. “The physical world does not respect reporting boundaries,” she said. “It would be very convenient if a flood stopped at the edge of the consolidation perimeter, but nobody sent the river our accounting manual. We need enough visibility beyond direct operations to understand the dependencies that matter. We start with the most significant or the least substitutable dependencies and improve the evidence over time. Procurement colleagues may know where alternatives exist. Suppliers may understand constraints that our internal forecasts miss. For finance teams, the question is which external dependency could invalidate an important assumption in our plan. And to find that out, you need to work across your organisation.”
Leadership role
Watson’s vision is for accountants to take the lead across departments, asking the right questions, interrogating assumptions, building trust and understanding the consequences of every action – and inaction. Delay can bring greater disruption, more expensive solutions and fewer future options.
“Take a supplier outage,” she said. “What happens to revenue and working capital, and how does the cost of building resilience compare with the cost of waiting? Second, how about dependencies and sources of value – what are we relying on that our decisions overlook? It might be water availability, a critical supplier or workforce. Choose one dependency and trace what its loss would mean financially. Third, the time horizon – which assumption in our forecasts or asset valuation needs challenging right now? Test the plausible exposure over the life of the investment. Ask whether that evidence changes the investment case or calls for a reassessment of the valuation assumptions.
“Finally, what material information is missing that could change our decision? Use the best available evidence. Make estimates and assumptions explicit, test how sensitive the decision is, and agree what new evidence would trigger a review. Keep improving data quality while exercising professional judgement today.
“Imagine a board paper that clearly explains which dependency matters, how it affects the investment case, and what would trigger a reassessment,” added Watson. “That helps the board give oversight. It also gives the eventual reporting a stronger foundation, building credibility with increasingly sceptical and fickle capital markets. That is how we connect the evidence to decisions, and give people a reason to trust the reporting. And it’s trust that is central to all of this.”
A question
of trust
Fiona Watson believes that accountants are critical to steering business through the climate change crisis. In her ICAS Sustainability Summit 2026 keynote speech, she explored how CAs have the skills to interrogate assumptions, understand consequences and provide assurance. Fraser Allen reports
Fiona Watson may jokingly refer to herself as “an amateur accountant” but 25 years of experience across law, banking and sustainability have led her to believe that it’s time for the accountancy profession to step up and tackle the complex challenges of sustainability. “My boss, Peter Bakker, once said that accountants will save the world,” she told the ICAS Sustainability Summit 2026 in Edinburgh in October. “If that’s true, we certainly have work to do.”
Watson is Vice President, Corporate Performance & Accountability at the World Business Council for Sustainable Development (WBCSD), an association of around 230 large organisations “leaning into the sustainability challenge”. Although based in Amsterdam following spells working in New York and London, Watson is originally from Edinburgh – she was Head of Legal for Treasury, Disclosure and ESG at RBS Group (now NatWest) in the aftermath of the financial crisis, from 2011–20. She also worked in senior roles for Amazon in Luxembourg and Amsterdam from 2020–23 where she led on EU Green Deal and global ESG reporting initiatives.
A quick look back at this year’s ICAS Sustainability Summit
A quick look back at this year’s ICAS Sustainability Summit
The dual-qualified lawyer (in both the UK and the US) therefore brought a wealth of experience to the summit, and began her keynote speech by looking forward to 31 December 2030 – the deadline for achieving the United Nations’ 17 Sustainable Development Goals.
“When we look back in 2030, what will we want to say we helped to achieve or helped avert?” she said. “The contribution of the profession of accountants is to help test the business case, including the assumptions about execution and financial returns. We need to trace each relevant exposure to the financial consequences – that is where accountants can make the evidence useful. You bring the experience in controls and professional judgement.”
Starting point
“Long before change happens and appears in a report, it appears in decisions,” Watson added. “A forecast assumes something about future costs and demand. An investment proposal assumes an asset will operate under certain conditions. A procurement decision assumes that a supplier will keep delivering. Those assumptions all shape the outcomes we eventually report. However, if we wait until the outcome appears in the report, some of our opportunities to respond may already have passed.”
Watson urged CAs to think about one significant decision their organisation is currently making. “How long will its consequences last? What conditions does it depend on? What evidence would make you pursue a different course?”
“It would be very convenient if a flood stopped at the edge of the consolidation perimeter, but nobody sent the river our accounting manual”
Critical to this is the concept of ‘double materiality’ that urges businesses to both assess their impact on the environment and the environment’s impact on them. “But it starts with a decision,” said Watson. “What could change the outcome enough to matter? What does the business depend on? What consequences could its activities create for others, and how might those consequences change the conditions in which it operates? For example, a water-intensive business may depend on reliable access to water but it may also affect local water availability. Understanding both perspectives can improve the questions that management asks about building its resilience.”
But as Watson points out, nothing is clear-cut. “The physical world does not respect reporting boundaries,” she said. “It would be very convenient if a flood stopped at the edge of the consolidation perimeter, but nobody sent the river our accounting manual. We need enough visibility beyond direct operations to understand the dependencies that matter. We start with the most significant or the least substitutable dependencies and improve the evidence over time. Procurement colleagues may know where alternatives exist. Suppliers may understand constraints that our internal forecasts miss. For finance teams, the question is which external dependency could invalidate an important assumption in our plan. And to find that out, you need to work across your organisation.”
Leadership role
Watson’s vision is for accountants to take the lead across departments, asking the right questions, interrogating assumptions, building trust and understanding the consequences of every action – and inaction. Delay can bring greater disruption, more expensive solutions and fewer future options.
“Take a supplier outage,” she said. “What happens to revenue and working capital, and how does the cost of building resilience compare with the cost of waiting? Second, how about dependencies and sources of value – what are we relying on that our decisions overlook? It might be water availability, a critical supplier or workforce. Choose one dependency and trace what its loss would mean financially. Third, the time horizon – which assumption in our forecasts or asset valuation needs challenging right now? Test the plausible exposure over the life of the investment. Ask whether that evidence changes the investment case or calls for a reassessment of the valuation assumptions.
“Finally, what material information is missing that could change our decision? Use the best available evidence. Make estimates and assumptions explicit, test how sensitive the decision is, and agree what new evidence would trigger a review. Keep improving data quality while exercising professional judgement today.
“Imagine a board paper that clearly explains which dependency matters, how it affects the investment case, and what would trigger a reassessment,” added Watson. “That helps the board give oversight. It also gives the eventual reporting a stronger foundation, building credibility with increasingly sceptical and fickle capital markets. That is how we connect the evidence to decisions, and give people a reason to trust the reporting. And it’s trust that is central to all of this.”
From risk to decision-making
During her presentation, Fiona Watson referred to a discussion paper published by WBCSD in September, called From Physical Risk to Financial Decision-Making: A diagnostic and maturity model for Corporate Finance and FP&A. Download this free paper to explore the topic.
From risk to decision-making
During her presentation, Fiona Watson referred to a discussion paper published by WBCSD in September, called From Physical Risk to Financial Decision-Making: A diagnostic and maturity model for Corporate Finance and FP&A. Download this free paper to explore the topic.
 Built with Shorthand